

Welcome to Mortgage Lending Explained, my consumer education blog dedicated to bringing clarity to the mortgage process.
Mortgage Lending Explained is published on Substack at www.JSWhaldo.Substack.com and is also featured here on JSWhaldo.com. Wherever you choose to read, I encourage you to comment, ask questions, and subscribe.
The Mortgage Lending Explained newsletter is published with each new article and podcast episode. My monthly JSWhaldo newsletter focuses primarily on travel and lifestyle content, highlighting new projects and stories from across the site.
After more than 30 years in mortgage underwriting, I write these articles to help consumers understand how mortgage loans really work. My goal is to explain lending in plain English, separate fact from fiction, and provide insight into how mortgage underwriters evaluate loan applications.
Whether you're buying your first home, refinancing, exploring reverse mortgages, or simply curious about credit and lending, I hope you'll find useful information and practical answers here.
Written by J.S. Whaldo, a retired mortgage underwriter with more than three decades of industry experience.
Welcome, and enjoy exploring Mortgage Lending Explained.
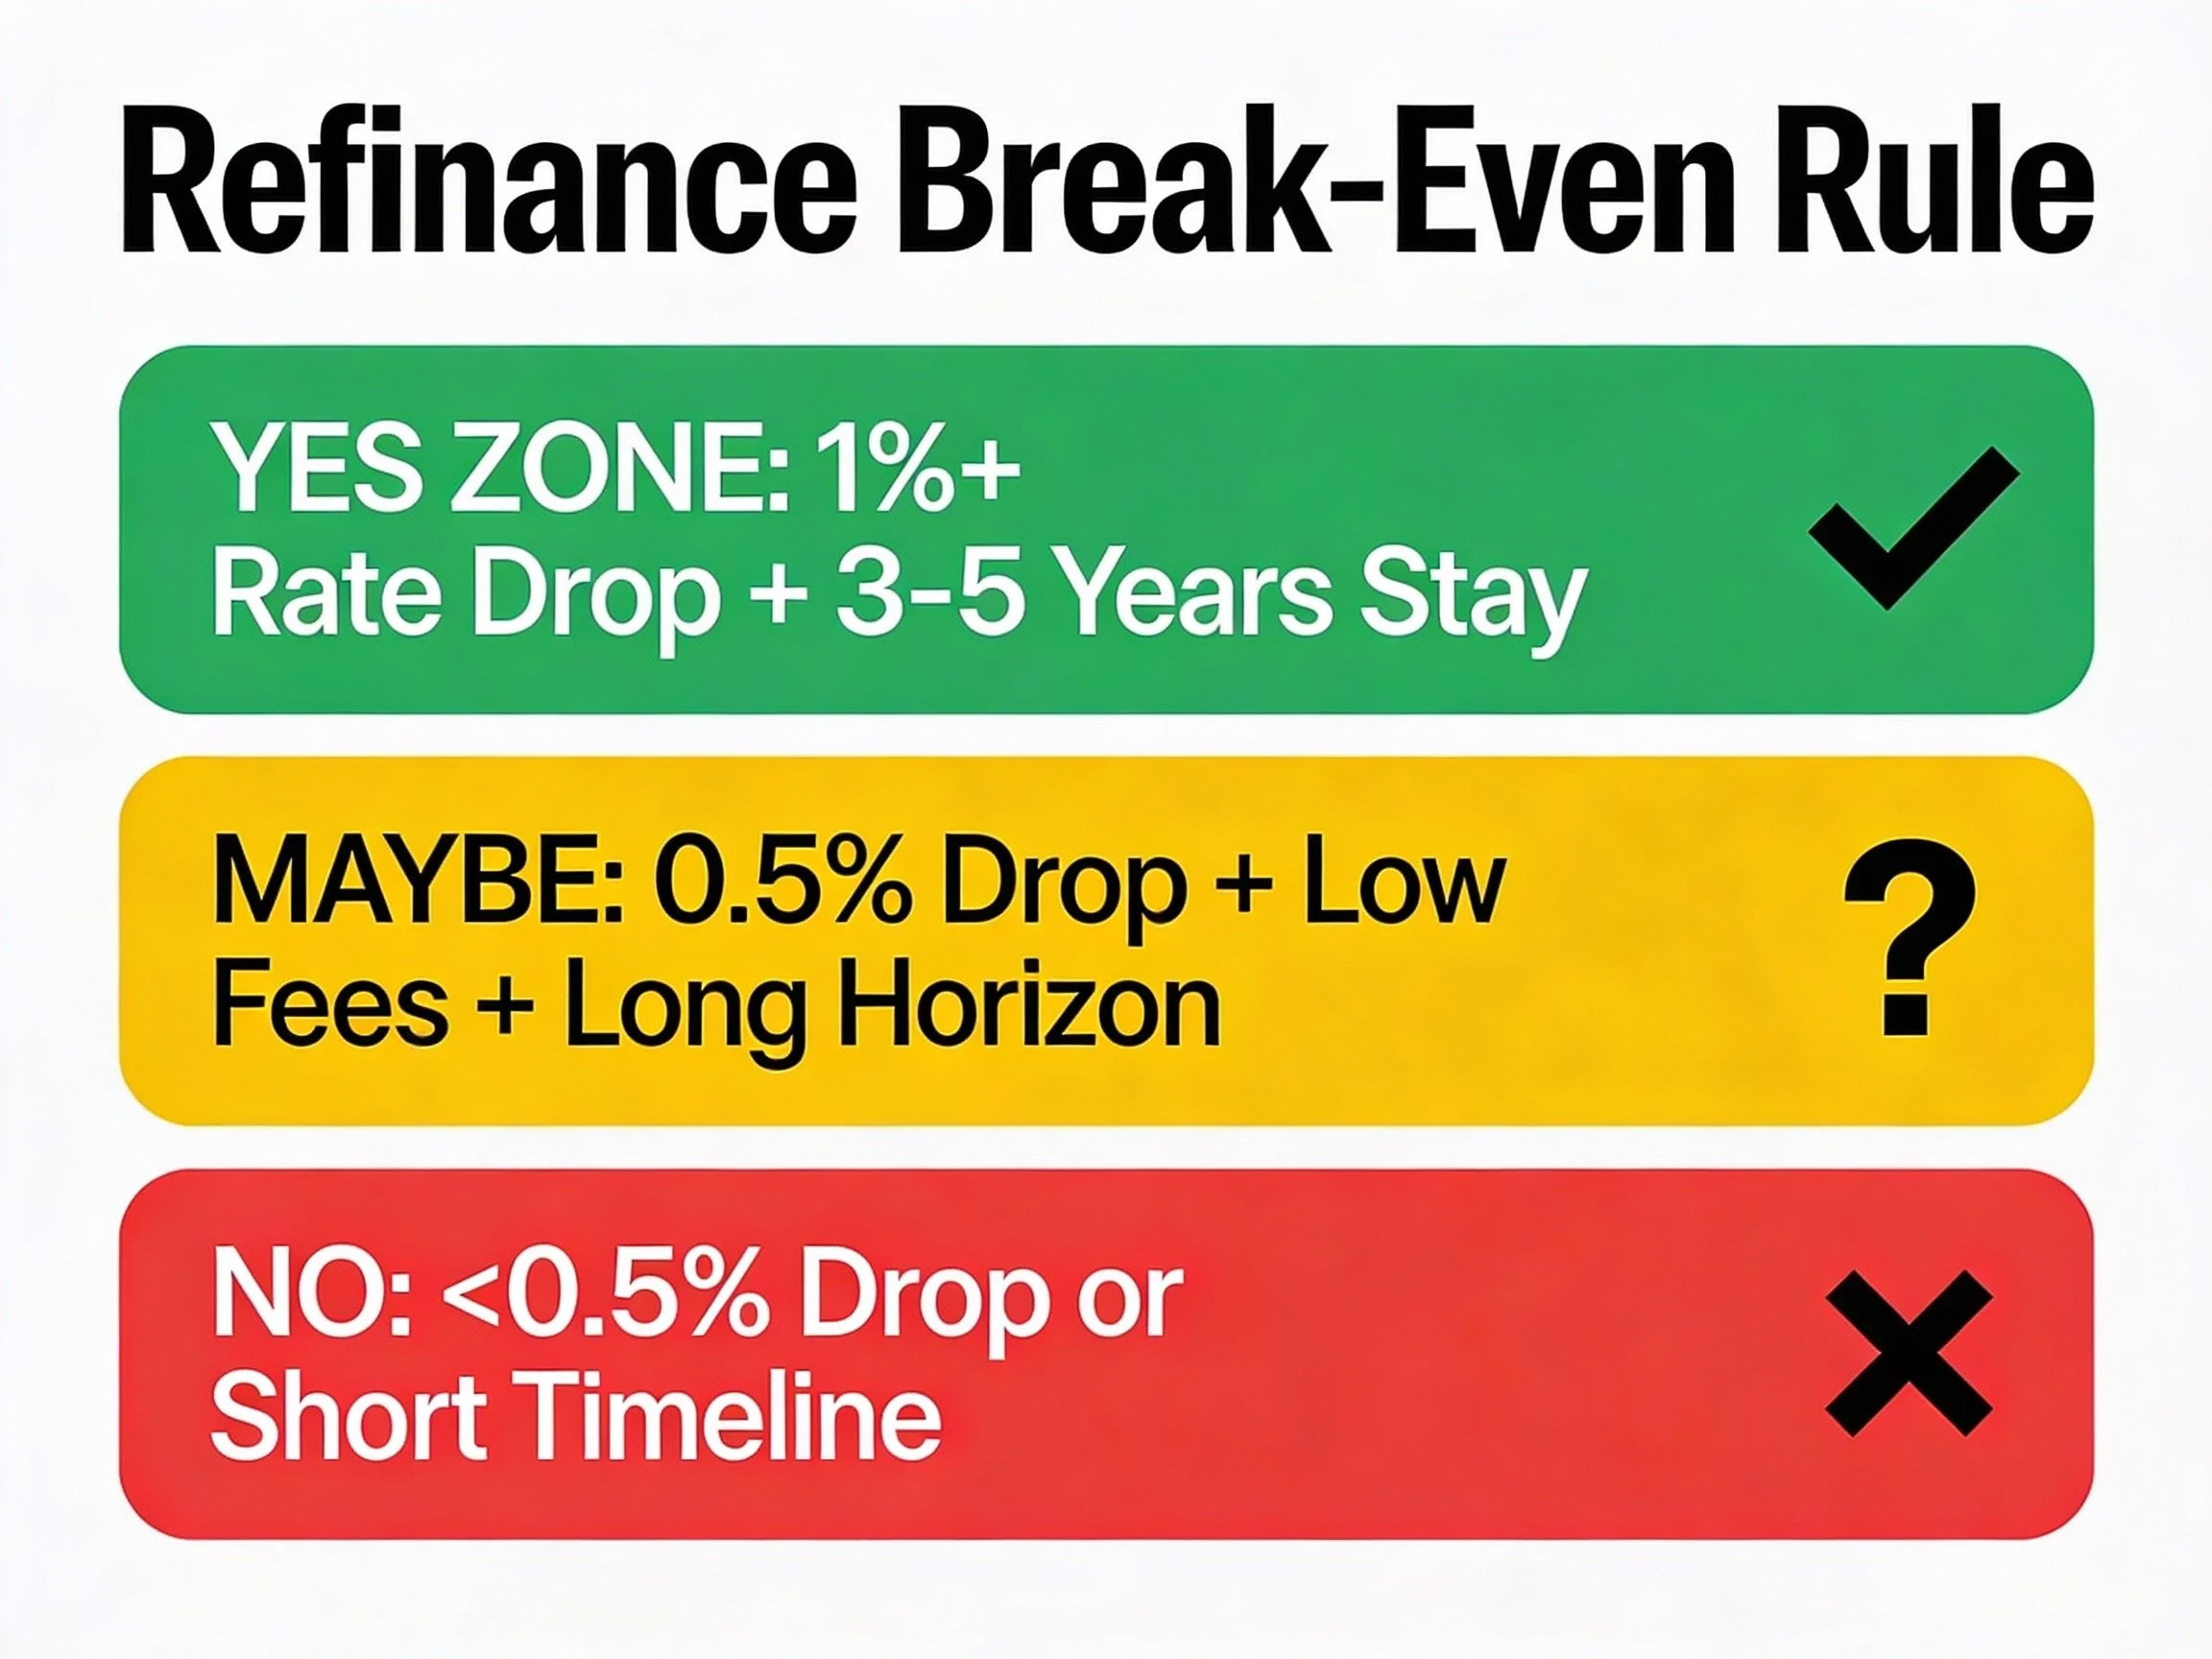
When a Mortgage Refinance Makes Sense and When It Does Not
When does a refinance actually put money in your pocket, and when is it just moving numbers around?
FHA Gift Funds Rules That Can Make or Break Your Mortgage
FHA Gift Fund Rules, Documentation Requirements, and Approved Donors for Smooth Mortgage Closings
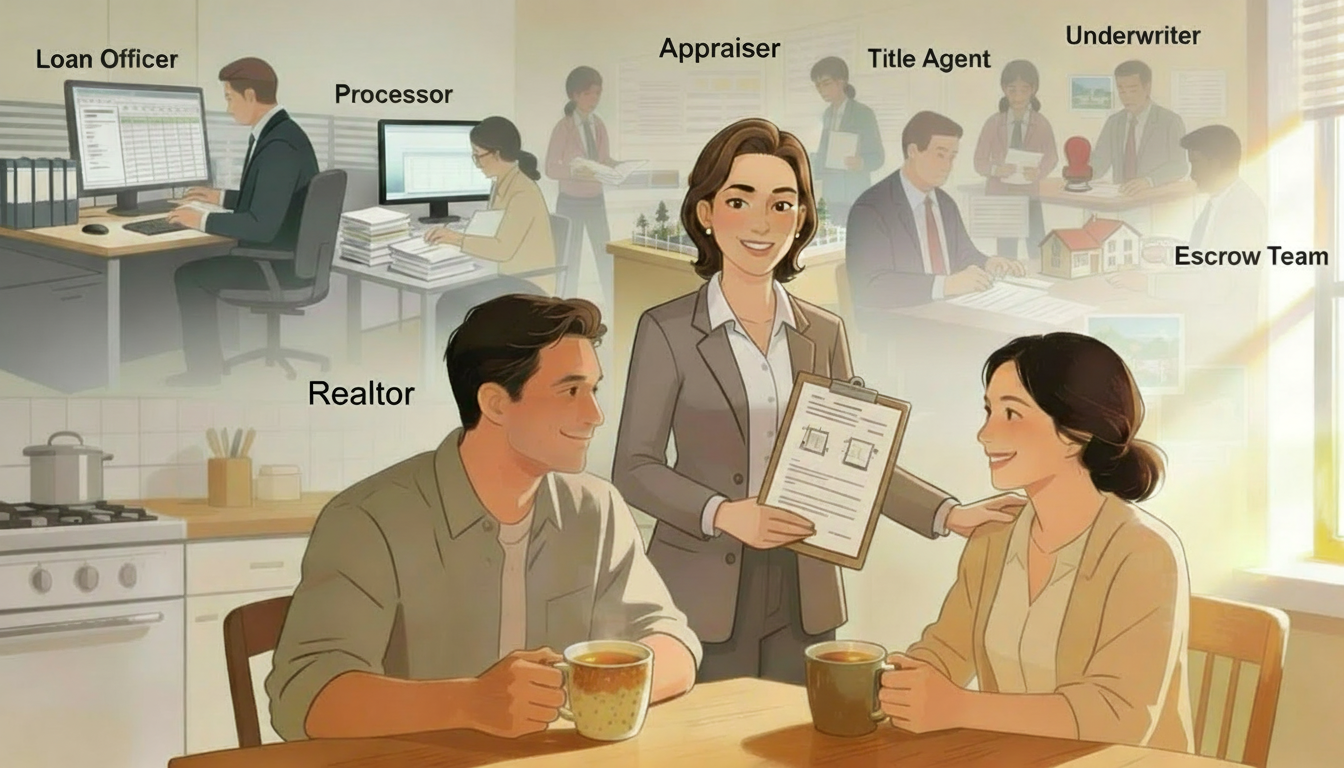
Inside the Mortgage Process from Application to Closing
Buying a home is exciting, but the mortgage process can feel like stepping into a house where every door opens to another room you didn’t know existed.
If you’ve ever wondered why the process feels complex or why so many people are involved, this is your guided walk-through of what happens from the moment you apply to the moment your loan closes.
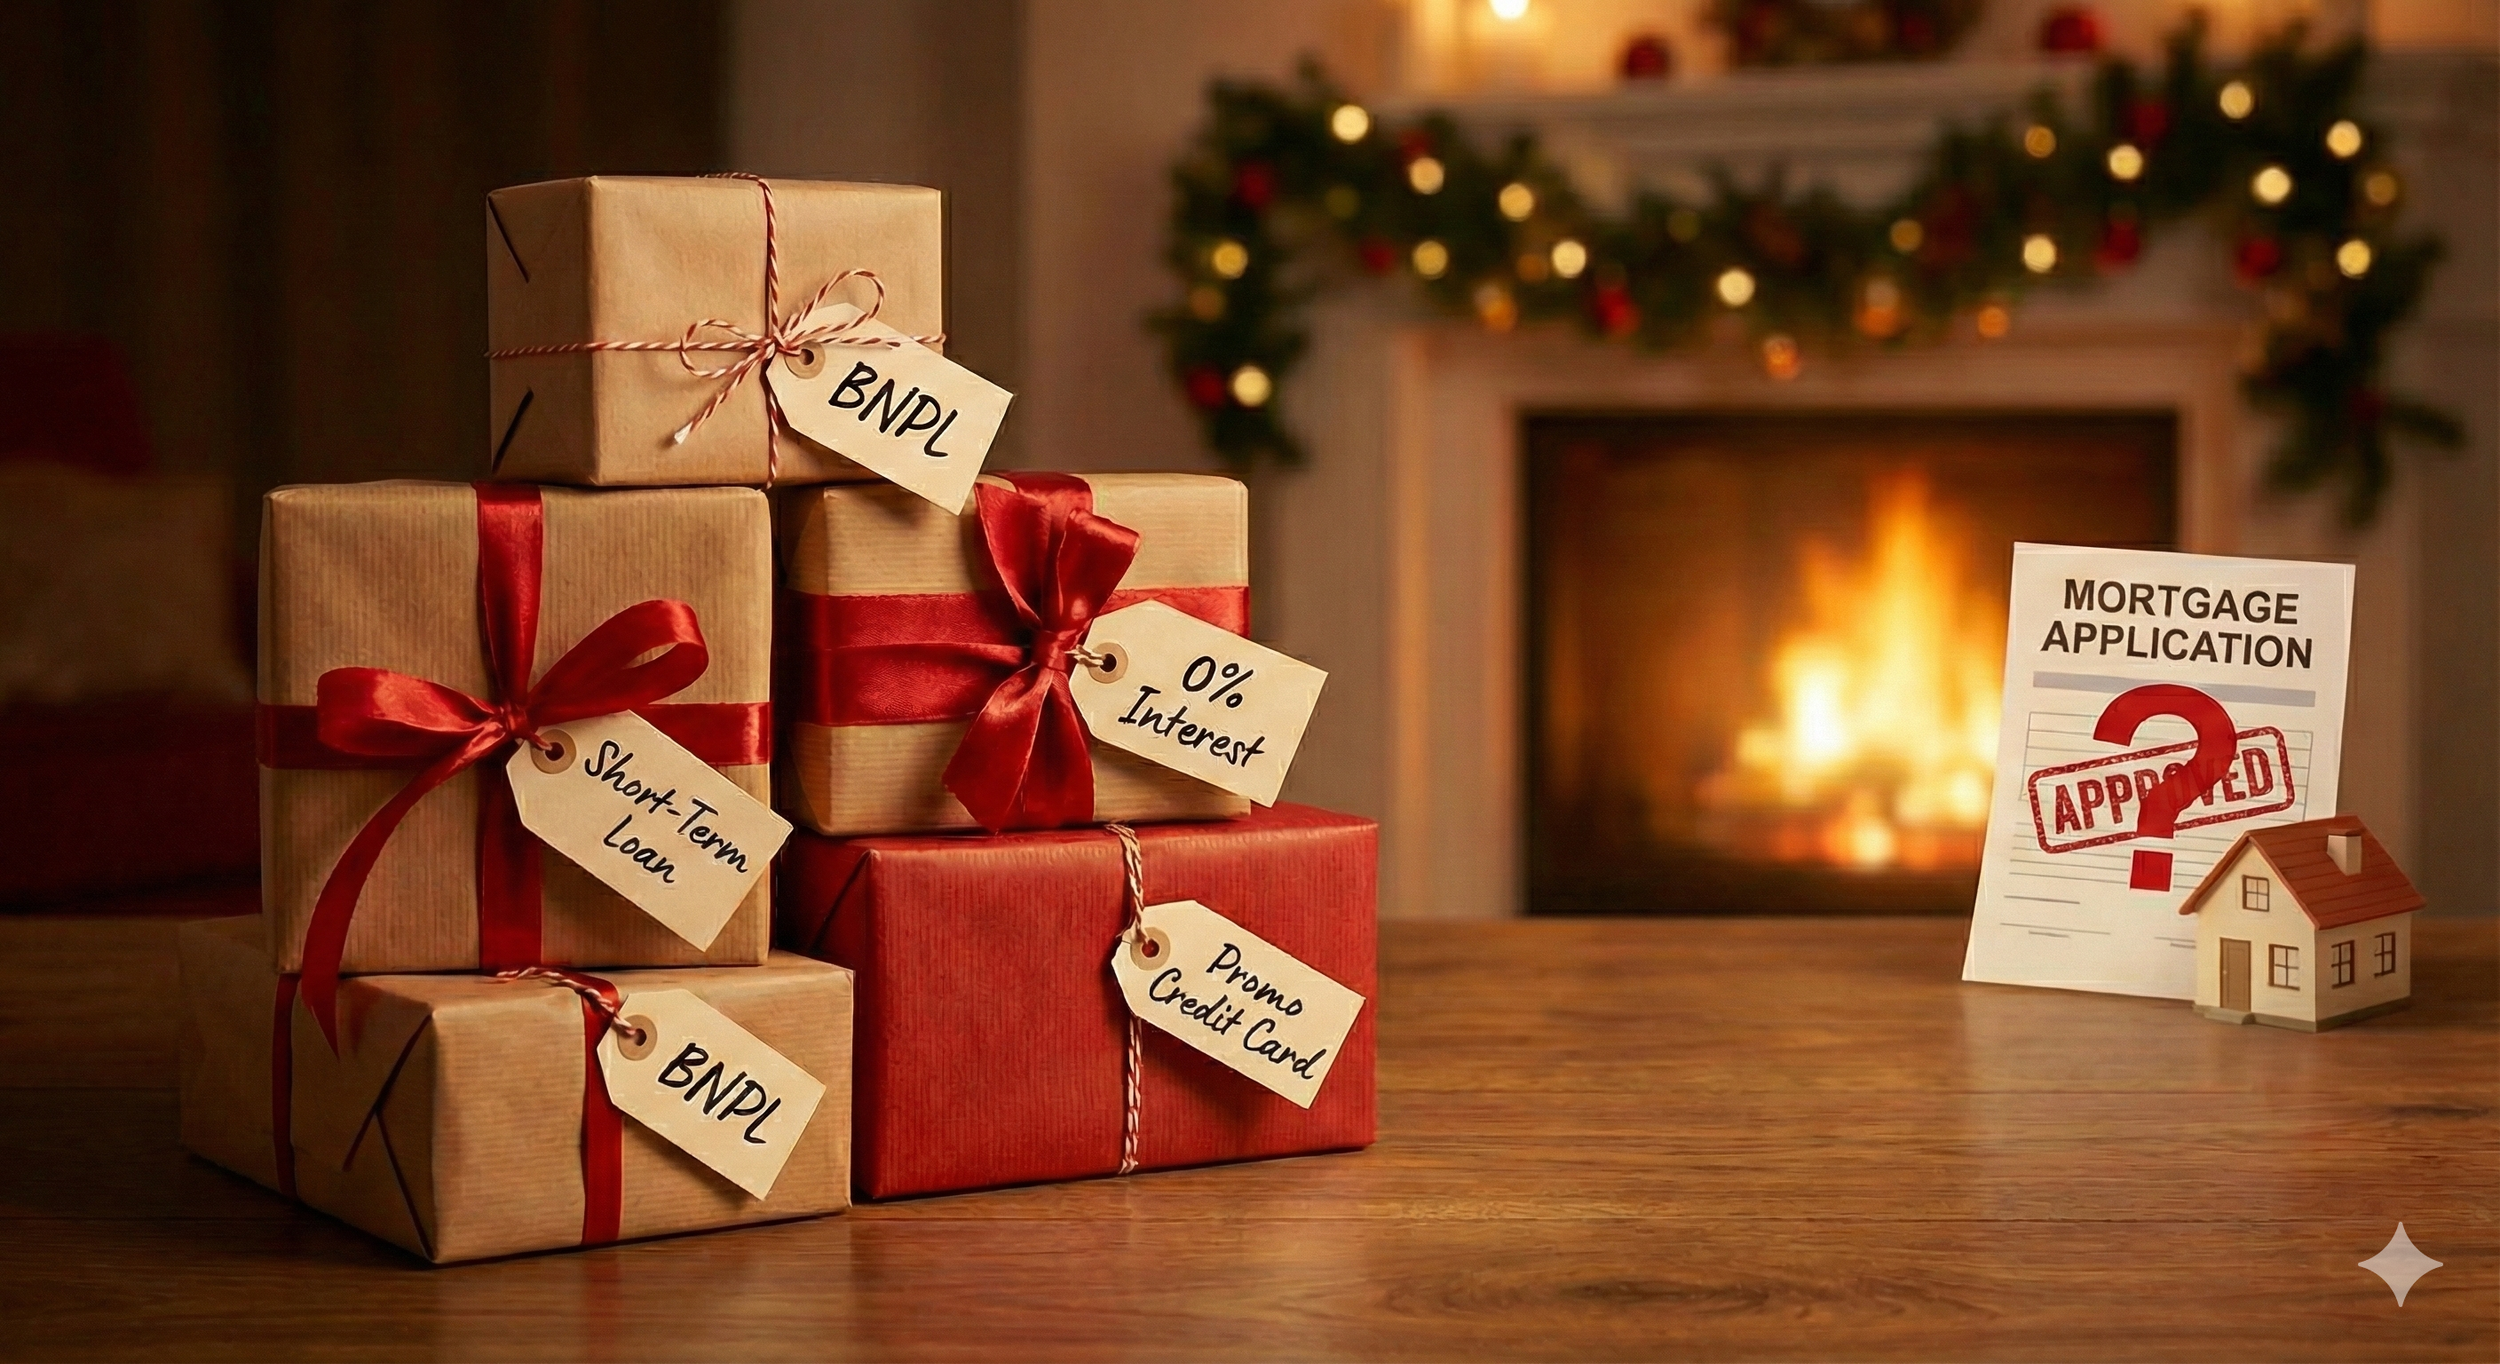
The Holiday Money Moves That Can Kill Your Mortgage Approval
After more than thirty years of underwriting, I can tell you that these little holiday spending choices show up in mortgage files like breadcrumbs. Buy Now Pay Later plans, short-term loans, zero-interest cards, promo-rate balance transfers, all of it adds up. And during the busiest shopping season of the year, borrowers accidentally make their mortgage path harder without realizing they’re doing anything risky at all.
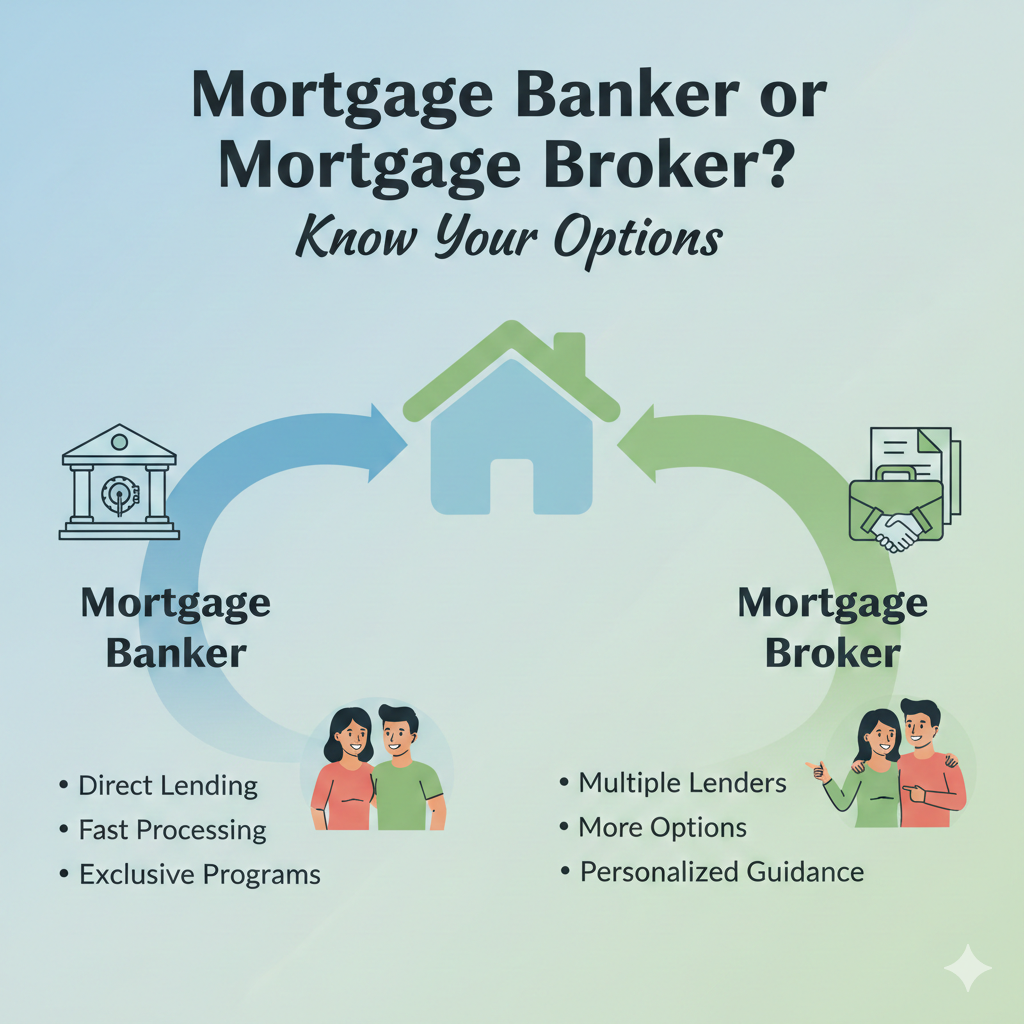
Mortgage Bankers or Mortgage Brokers - Which One Is Right for You
Working with the right professional can save you both time and money. One key decision is whether to go with a mortgage banker or a mortgage broker. Both can help you secure a loan, but they do it in very different ways.

Common Mistakes That Can Delay Your Mortgage Approval
I can honestly tell you that throughout my career, many people have lost their mortgage approval near the end because of avoidable mistakes. It happens far more often than most buyers expect. Here is what you should avoid altogether.
What You Need To Know About Down Payment Assistance with a Shared Appreciation Mortgage
A SAM is usually a second mortgage that stays “silent.” That means no interest, no monthly payments, and repayment only happens when the home is sold or transferred. When that time comes, you pay back the original loan plus a share of any increase in your home’s value, called appreciation.
Understanding Down Payment Assistance: A Simple Guide for Homebuyers
Over the years, I’ve heard countless people say the same thing: “I’d buy a home if I could just save for the down payment.” It’s not an excuse, it’s a real challenge. Between rising costs and everyday bills, most families find it difficult to save enough to get started. That’s why down payment assistance programs are so important.
Physician Mortgage Loans Explained: Pros, Cons, and What Doctors Need to Know
Fresh out of residency, staring down the mountain of student loans, and dreaming about buying a house? Someone may have whispered the magic words: “physician mortgage loan.” Sounds like it was custom-built just for you, right? Well, kind of. Let’s break it down without the jargon.

Student Loans and Mortgages: What You Need to Know
Even if your student loan is in deferment, most lenders still count a monthly payment in your debt-to-income ratio, or DTI. The tricky part is that each loan program has its own rules. That means the same $75,000 loan balance could be treated very differently depending on whether you apply for a VA, FHA, USDA, or Conventional loan.
Self-Employment Qualifying Income: C-Corps Made Simple
Finishing the Self-Employment Series: C-Corp Income Made Clear for Mortgage Qualification
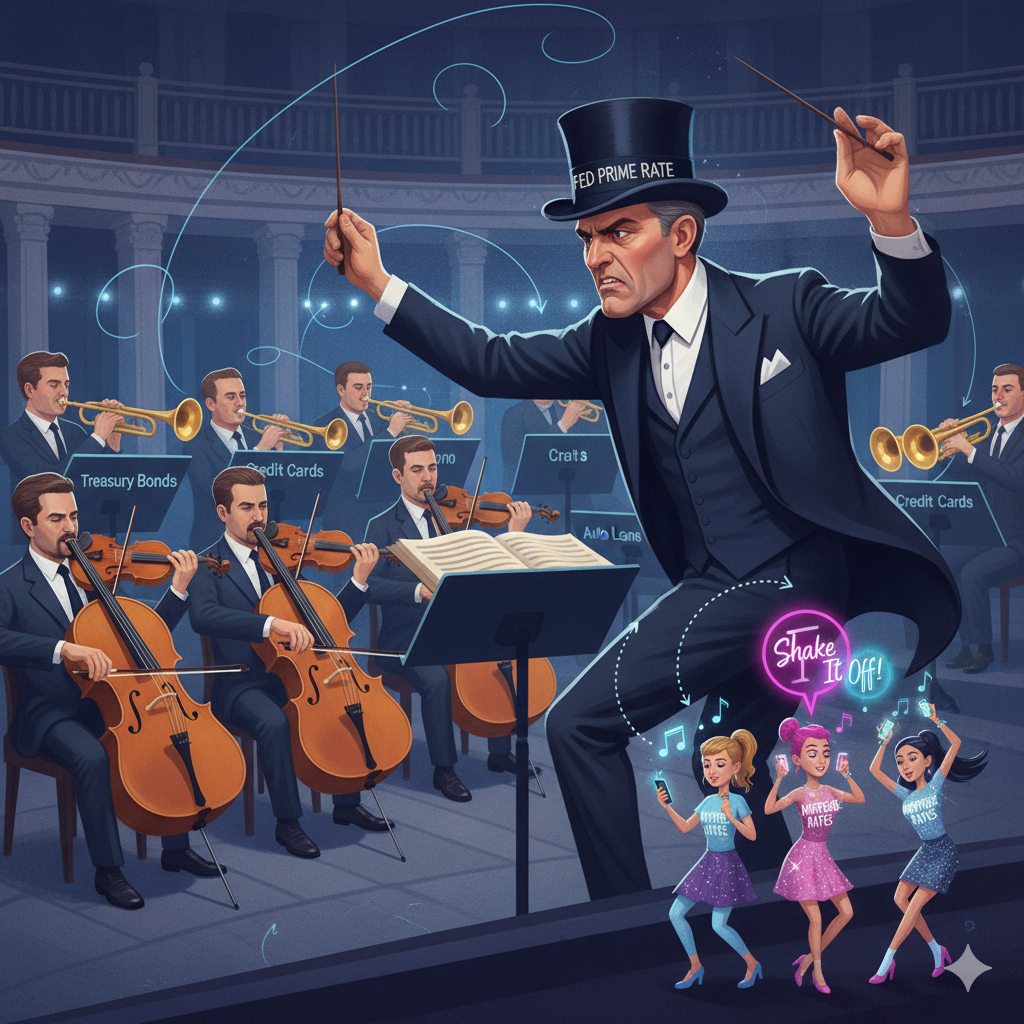
Mortgage Rates: Dancing to Their Own Beat
When the Federal Reserve reduces the Prime Rate, people often expect mortgage rates to drop right away. It feels like they should be connected, but they are not.
Self-Employment Qualifying Income: S-Corporations Made Simple
S-Corp Income: What Counts for Your Qualifying Income and What Doesn’t
Self-Employment Qualifying Income: Partnerships Made Simple
If you own a partnership, determining which income counts towards a mortgage can be confusing. In this article, I’ll walk you through how mortgage underwriters determine qualifying income from partnerships. I’ll show you how to use your K-1 and the partnership’s 1065 tax return, with a practical example, so you can see exactly how it works.
Self-Employment Qualifying Income: Understanding Sole Proprietor Schedule C Earnings
How Mortgage Underwriters Determine Qualifying Income From Your 1040 Schedule C.
Self-Employed and Applying for a Mortgage? Start Here
We’re breaking down the different types of businesses and the documents lenders need so you can see exactly what counts as income.
Qualifying Income from Part-Time Jobs, Seasonal Work, and Side Gigs
How Underwriters Evaluate Part-Time Jobs, Seasonal Work, and Side Gigs for Mortgage Qualification
How Lenders Calculate Your Mortgage Qualifying Income: Commission Income and Schedule C (Sole Proprietorship)
Income Basics: How Lenders Calculate Your Qualifying Income for a Mortgage Part Two
How Lenders Calculate Your Mortgage Qualifying Income: Salary, Hourly, Overtime/Bonus Explained
Over the past few weeks, we’ve talked about credit, liabilities, debt-to-income, and assets.
Now, we’re moving into one of the most important, and often confusing, parts of getting a mortgage: income calculation.
Understanding Allowable Funds: What Counts, and What Doesn’t - When You're Qualifying for a Mortgage
Welcome to part two of our asset series. This time, we’re diving into allowable funds: the money you’ll use for your down payment and closing costs. These funds need to be verified, seasoned, and ready to go when it’s time to close. And while it’s easy to assume that money is money, mortgage underwriters see things differently.